
Logistics & Light Industrial
Logistics and light industrial is one of Slättö's two conviction segments, supported by resilient occupier demand, improving macro conditions and growing e-commerce activity.
Activity is accelerating and yields have compressed
Investment market
The segment has remained resilient through the cycle and activity has accelerated: H1 2026 transaction volumes were 49% higher than H1 2025 and 46% above the ten-year H1 average, with Sweden and Finland at record levels while Denmark and Norway were relatively slow. Prime yields compressed slightly across all countries. The yield spread between logistics and light industrial has narrowed to more balanced levels from its 2022 peak, with recent transactions showing notable portfolio premiums in light-industrial. Finland still stands out with higher yields and a wider spread than the other Nordic markets.

Occupier market
Leasing momentum has strengthened, supported by resilient occupier demand, improving macro conditions and growing e-commerce activity. Logistics vacancy remains elevated in areas affected by earlier speculative development but is gradually rebalancing as new supply slows, while light-industrial vacancy stays low with selective upward pressure on rents in constrained submarkets. In Denmark, construction fell sharply in 2025 and land scarcity around Copenhagen continues to limit large-scale development, pushing major platforms outward to hubs such as Ringsted. In Norway, prime last-mile rents in Oslo have risen sharply since 2022 and now exceed NOK 2,000 (roughly EUR 170) per sqm and annum.
Transaction volumes are up 49% year-on-year and 46% above the ten-year H1 average, led by Sweden and Finland, with prime yields having compressed from peak.
Occupier markets are improving as speculative supply slows, light-industrial stays tight, and portfolio premiums underpin the roll-up strategy.
Leasing momentum is strengthening
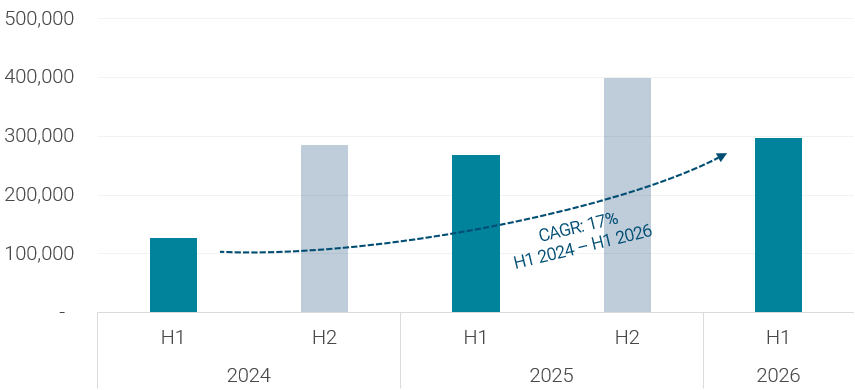
Announced lettings in Sweden 2024-26. Data: Colliers and Dagens Logistik
Following several years of elevated development activity, the Swedish logistics market is entering a more balanced phase. Higher financing costs, increased vacancy and stricter return requirements have significantly reduced speculative construction, with new development increasingly driven by occupier demand and build-to-suit projects.
At the same time, development is becoming more selective and concentrated in strategic logistics hubs and well-connected locations that can support modern occupier requirements.
The market is shifting towards a more disciplined and demand-led development cycle, supporting healthier long-term fundamentals.
Development is becoming more selective
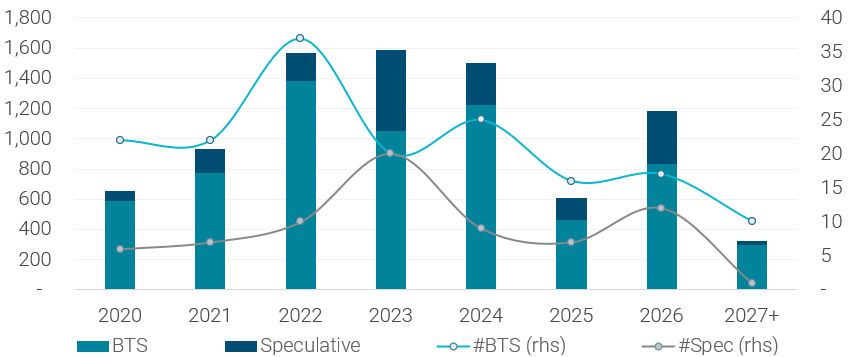
New developments per year in Sweden 2015-27+. Data: Croisette